Why Strong Mortgage Networks Keep Brokers Close to Lenders: In business, distance rarely improves understanding. The further people move from the source of a decision, the easier it becomes for meaning to be reduced to rules, numbers and assumptions.
Mortgage lending is no different.
A broker can read criteria, compare rates and search for products. Yet none of those things fully explains how a lender is thinking, where its appetite is changing, or why one case may be welcomed while another receives closer scrutiny.
That knowledge sits closer to the source.
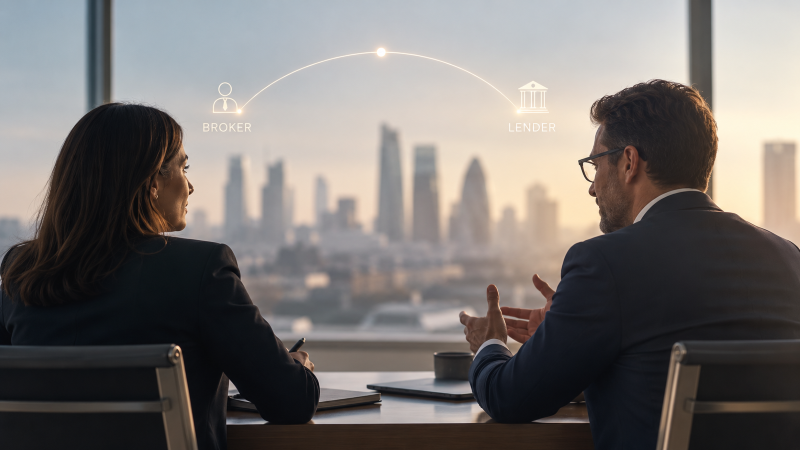
This is why strong mortgage networks do more than provide access to lenders. They reduce the distance between the adviser asking the question and the lender shaping the answer.
Strong mortgage networks understand a simple truth: distance changes understanding.
The further a broker sits from a lender, the easier it becomes to see criteria as rules alone.
Yet lending has never been only about rules.
Behind every policy sits an appetite. Behind that appetite sits a commercial decision.
Behind every decision sits a lender deciding which borrowers, properties and circumstances it wants to support.
That distinction matters.
A strong mortgage network does more than give brokers access to lenders.
It keeps advisers close enough to understand how those lenders think.
For brokers, that can make the difference between finding a product and understanding whether a case genuinely fits.
Lender Access Is Only the Beginning
Most brokers expect their mortgage network to provide access to lenders.
That expectation is reasonable.
However, a lender panel alone says little about the quality of the relationship behind it.
A network may offer hundreds of lender names.
The more important questions are different.
Can brokers speak to people who understand the lender?
Can difficult cases receive meaningful attention?
Do advisers hear about criteria changes quickly?
Can the network explain what a lender wants before an application reaches underwriting?
Does useful broker feedback reach lenders?
These questions reveal the difference between lender access and lender connection.
Access opens a door.
Connection helps the broker understand what sits behind it.
For advisers comparing networks, our guide to joining a UK mortgage network explains why lender access should form only one part of the decision.
Criteria Tell You What. Relationships Can Explain Why
Mortgage criteria are essential.
They establish boundaries around loan-to-value, income, property, credit history and borrower circumstances.
Yet a criteria search cannot always explain the thinking behind a lending decision.
Consider two cases that appear almost identical.
One may fit comfortably.
Another may raise questions because of income structure, property type or the wider application.
The difference often lies in the details.
That is where communication becomes valuable.
Strong mortgage networks help lenders and brokers understand each other better.
Lenders can explain their appetite.
Brokers can explain what clients are actually bringing to the market.
Both sides gain knowledge.
The FCA’s requirements for mortgage brokers also reinforce the importance of suitability, customer understanding and appropriate support throughout the advice process.
A Broker Should Know More Than the Rate
Rates matter.
So do fees, incentives, affordability calculations and lending limits.
However, good mortgage advice requires context.
A competitively priced mortgage has little value if the application doesn’t meet the lender’s requirements.
Experienced brokers therefore need to understand questions such as:
- How does the lender assess complex income?
- Which property types require closer assessment?
- How are portfolio landlords considered?
- What evidence strengthens a specialist application?
- Where might an underwriter require more information?
- What causes avoidable referrals?
- What information should be supplied from the beginning?
This knowledge is especially important in specialist lending.
Buy-to-let, commercial finance, bridging and complex residential lending can involve more variables.
A specialist mortgage network for advisers should therefore offer more than a list of lenders.
Closer lender relationships can help brokers ask better questions before submitting cases.
Good Networks Create Conversations, Not Just Panels
A philosophical difference separates collecting lender relationships from developing them.
One measures quantity.
The other builds knowledge.
Strong mortgage networks bring lenders into the adviser community through meetings, training, events, webinars and direct communication.
Those exchanges matter because mortgage lending is constantly changing.
Policy changes.
Affordability models change.
Property appetite changes.
Funding conditions change.
A lender may become more interested in one part of the market while reducing appetite elsewhere.
A broker who sees only the published product may not understand what has changed.
A broker involved in the wider conversation may also understand why.
That distinction can matter when explaining possibilities to a client.
Lenders Need Brokers Too
The relationship should never be viewed as one-sided.
Brokers need lenders.
Lenders also need knowledgeable brokers.
Intermediaries see borrower circumstances before lenders do.
They hear what landlords are planning.
They understand where first-time buyers are struggling.
They see how self-employed applicants structure income.
They encounter unusual properties and complex borrowing requirements.
That gives the intermediary market something valuable: perspective.
A strong mortgage network can bring those experiences together.
Instead of one broker raising one issue, a network can identify themes across many advisers.
That can help lenders understand what is happening beyond their own application data.
The conversation becomes more useful for everyone.
Closer Lender Relationships Can Support Case Placement
A difficult mortgage case rarely gets easier by reaching the wrong lender faster.
Sometimes the most useful decision is knowing where not to send it.
Strong mortgage networks can support advisers by combining lender access with experienced case placement.
The broker remains responsible for research and recommendations.
However, additional knowledge can help them consider suitable routes earlier.
This becomes particularly useful with circumstances involving:
- complex or multiple income sources;
- adverse credit history;
- portfolio property ownership;
- limited company structures;
- unusual construction;
- commercial elements;
- short-term finance;
- development projects;
- specialist buy-to-let requirements.
Connect’s wider mortgage network proposition includes access to mainstream and specialist lenders, plus case placement and referral routes.
Good placement begins before an application reaches a lender.
It begins with understanding.
Better Communication Can Reduce Avoidable Friction
Every unnecessary decline has consequences.
The broker loses time.
The lender uses resources assessing the application.
Most importantly, the client may experience delay and uncertainty.
Not every unsuccessful application can be avoided.
Nor should lender relationships replace research, suitability assessments or underwriting.
They can, however, improve the conversation before submission.
A broker who understands what evidence a lender expects can prepare more effectively.
A network with active lender relationships can help reinforce that knowledge.
The result can be a better-prepared application from the outset.
This also reflects the FCA’s focus on firms delivering appropriate Consumer Duty outcomes, including customer understanding and support.
Specialist Lending Makes Proximity More Important
Mainstream lending can sometimes appear straightforward.
Specialist lending rarely gives brokers that luxury.
A case may contain several moving parts.
The borrower may be self-employed.
The property may have mixed use.
The applicant may own several investment properties.
The deposit may come from a less common source.
A sourcing system can help identify published criteria.
It cannot always interpret the complete story.
This is where experienced people remain valuable.
Connect for Intermediaries supports advisers across mainstream and specialist markets.
That includes residential, buy-to-let, commercial, bridging and other complex borrowing areas.
The aim should not simply be to give advisers more lenders.
It should give them a stronger environment to assess more complicated client circumstances.
For cases requiring additional expertise, advisers can also consider the network’s specialist mortgage support.
Training Becomes More Valuable When Lenders Are Involved
There is a difference between learning about a lender and learning from one.
That distinction should matter to brokers choosing a mortgage network.
Direct lender training can help advisers understand:
- current lending appetite;
- common packaging problems;
- underwriting expectations;
- new product areas;
- target customer groups;
- property restrictions;
- affordability approaches;
- common reasons for referral.
This knowledge can improve future client conversations.
It can also help advisers identify potential problems earlier.
Training should therefore do more than satisfy a calendar requirement.
At its best, it changes how advisers think about cases.
Connect includes training, CPD and lender updates within its wider network support for mortgage brokers.
Strong Mortgage Networks Act as a Two-Way Bridge
A valuable network should not simply relay lender announcements to brokers.
Information should move in both directions.
Lenders need to know what advisers are experiencing.
Advisers need to understand what lenders are changing.
A network sits between those conversations.
That position brings responsibility.
It should listen carefully.
It should identify recurring issues.
It should clarify misunderstandings.
It should create opportunities for lenders and brokers to communicate.
It should make useful information easier to reach.
When that happens, the network becomes more than infrastructure.
It becomes part of the information flow that helps the mortgage market operate effectively.
Technology Cannot Replace the Relationship
Technology has transformed mortgage distribution.
Research systems can process huge amounts of information.
CRMs can reduce administration.
Digital applications can shorten parts of the mortgage journey.
Artificial intelligence will continue changing how advisers research and process information.
Yet faster information does not automatically create deeper understanding.
A system may indicate that a case meets selected criteria.
An experienced lender contact may spot another issue that needs attention.
The stronger model combines both.
Use technology for speed.
Use people for context.
Strong mortgage networks understand the difference.
This is also why advisers comparing networks should consider technology alongside lender relationships, compliance and case support.
Our guide on why brokers join a mortgage network explores how those areas work together.
What Should Brokers Ask Their Mortgage Network?
When comparing mortgage networks, advisers should look beyond the size of the lender panel.
Ask how those relationships work in practice.
How regularly do lenders meet network members?
Regular contact can provide insight beyond product announcements.
Can brokers access lender training?
Useful training should cover appetite, criteria and practical case considerations.
What happens when a case becomes complicated?
Understand what specialist case placement or referral support is available.
Does the network cover mainstream and specialist lending?
Your future client base may broaden beyond your current one.
Does broker feedback reach lenders?
A useful network should communicate in both directions.
Are the lender relationships active?
A logo on a lender panel isn’t the same as an active working relationship.
These questions reveal far more than panel numbers alone.
Brokers making a wider comparison may also find our mortgage adviser network checklist useful before making a decision.
The Real Measure of Lender Access
Perhaps the wrong question has been asked for too long.
Brokers often ask:
“How many lenders does the network have?”
A better question may be:
“How close will this network help me get to understanding those lenders?”
The difference is important.
A large panel creates possibility.
Knowledge makes that possibility useful.
Communication gives it context.
Experience helps turn information into professional judgement.
That is why strong mortgage networks keep brokers close to lenders.
Not because advisers need someone else to make decisions for them.
Quite the opposite.
They keep brokers close because better-informed advisers can make stronger decisions themselves.
Keeping Advisers Connected at Connect
Connect for Intermediaries supports brokers through access to more than 200 lenders and providers across mainstream and specialist markets.
However, the number alone is not the point.
The value sits in what surrounds that access.
Lender relationships, specialist knowledge, case placement, training and adviser support can help brokers understand where cases may fit.
That becomes increasingly valuable when straightforward lending stops being straightforward.
For advisers considering their next stage of growth, the question is therefore bigger than which network provides access.
Ask which network keeps you closest to the people, knowledge and conversations shaping lending decisions.
Because in mortgage advice, knowing where to look matters.
Understanding why can matter even more.
If that sounds like the type of network relationship your business needs, explore what it means to join Connect Network.